

Welcome to Grupo Spurrier
Grupo Spurrier is the leading company in the provision of strategic information on economic and political issues regarding Ecuador, which we monitor through Weekly Analysis and Análisis Semanal. We specialize in economic research, competition advice, market research, business plans, and workshops in economic scenarios and regulatory changes.
Weekly Analysis Briefs
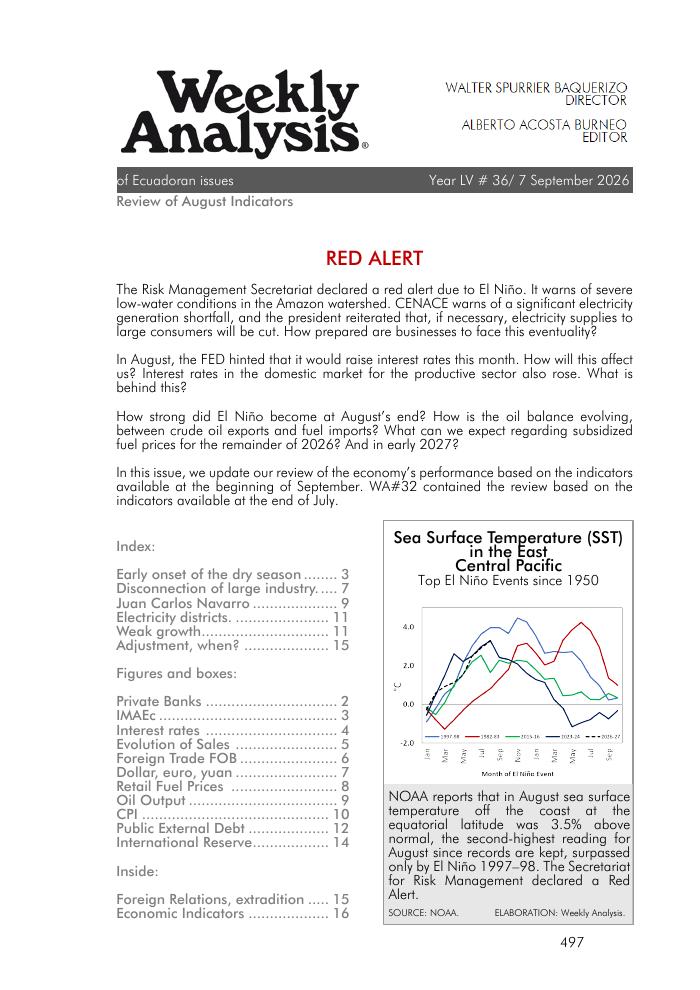
WA-2025-36: RED ALERT
The Risk Management Secretariat declared a red alert due to El Niño. It warns of severe low-water conditions in the Amazon watershed. CENACE warns of a significant electricity generation shortfall, and the president reiterated that, if necessary, electricity supplies to large consumers will be cut. How prepared are businesses to face this eventuality? In August, the FED hinted that it would raise interest rates this month. How will this affect us? Interest rates in the domestic market for the productive sector also rose. What is behind this? How strong did El Niño become at August’s end? How is the oil balance evolving, between crude oil exports and fuel imports? What can we expect regarding subsidized fuel prices for the remainder of 2026? And in early 2027? In this issue, we update our review of the economy’s performance based on the indicators available at the beginning of September. WA#32 contained the review based on the indicators available at the end of July.
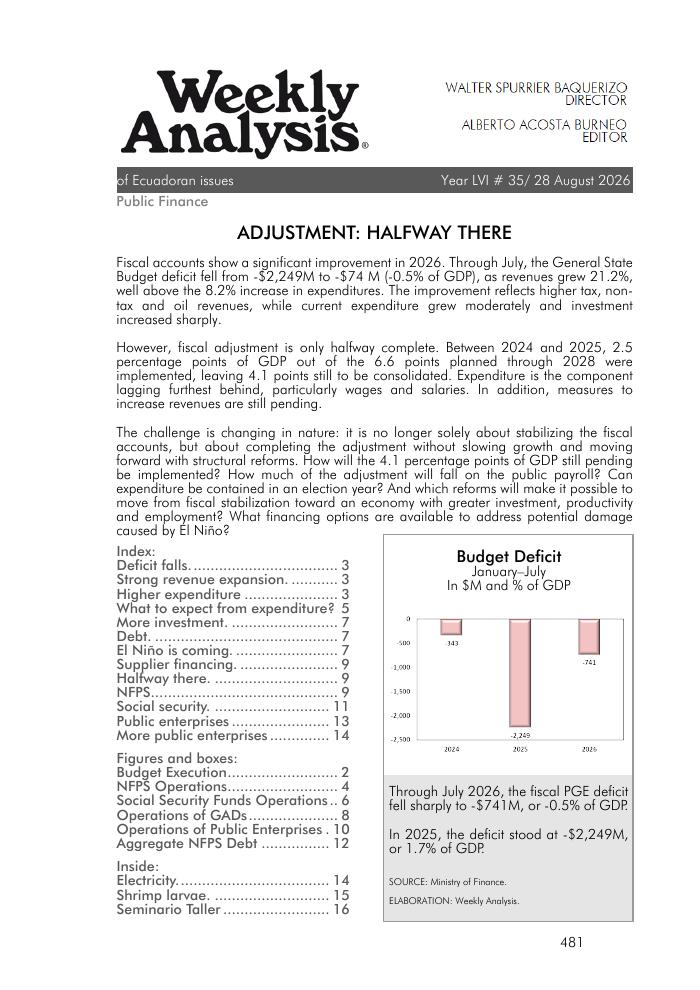
WA-2026-35: ADJUSTMENT: HALFWAY THERE
Fiscal accounts show a significant improvement in 2026. Through July, the General State Budget deficit fell from -$2,249M to -$74 M (-0.5% of GDP), as revenues grew 21.2%, well above the 8.2% increase in expenditures. The improvement reflects higher tax, non-tax and oil revenues, while current expenditure grew moderately and investment increased sharply. However, fiscal adjustment is only halfway complete. Between 2024 and 2025, 2.5 percentage points of GDP out of the 6.6 points planned through 2028 were implemented, leaving 4.1 points still to be consolidated. Expenditure is the component lagging furthest behind, particularly wages and salaries. In addition, measures to increase revenues are still pending. The challenge is changing in nature: it is no longer solely about stabilizing the fiscal accounts, but about completing the adjustment without slowing growth and moving forward with structural reforms. How will the 4.1 percentage points of GDP still pending be implemented? How much of the adjustment will fall on the public payroll? Can expenditure be contained in an election year? And which reforms will make it possible to move from fiscal stabilization toward an economy with greater investment, productivity and employment? What financing options are available to address potential damage caused by El Niño?
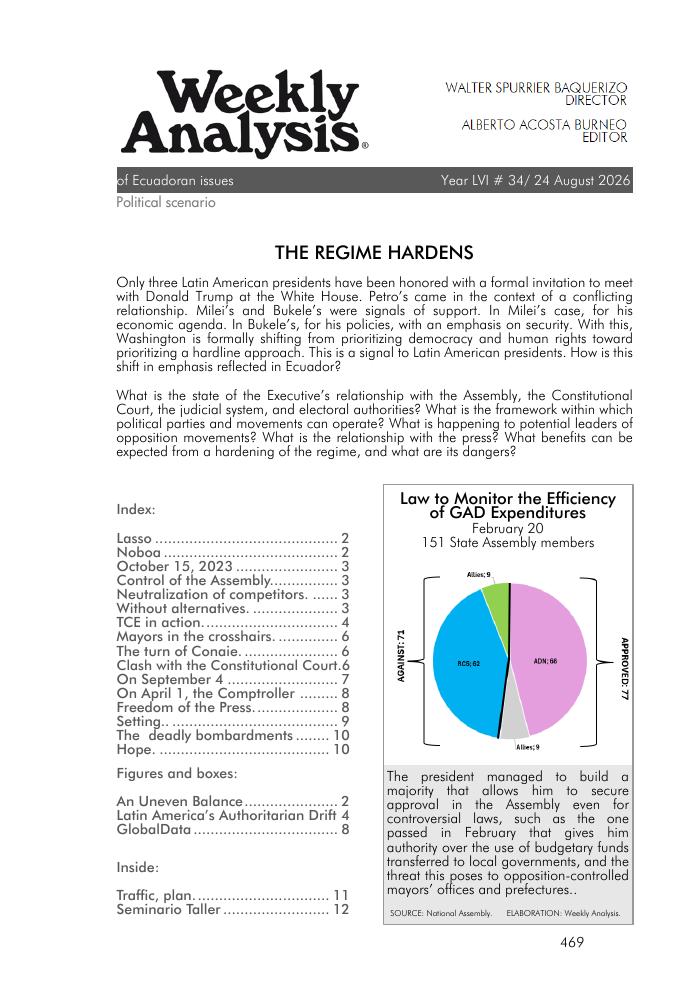
WA-2026-34: THE REGIME HARDENS
Only three Latin American presidents have been honored with a formal invitation to meet with Donald Trump at the White House. Petro’s came in the context of a conflicting relationship. Milei’s and Bukele’s were signals of support. In Milei’s case, for his economic agenda. In Bukele’s, for his policies, with an emphasis on security. With this, Washington is formally shifting from prioritizing democracy and human rights toward prioritizing a hardline approach. This is a signal to Latin American presidents. How is this shift in emphasis reflected in Ecuador? What is the state of the Executive’s relationship with the Assembly, the Constitutional Court, the judicial system, and electoral authorities? What is the framework within which political parties and movements can operate? What is happening to potential leaders of opposition movements? What is the relationship with the press? What benefits can be expected from a hardening of the regime, and what are its dangers?
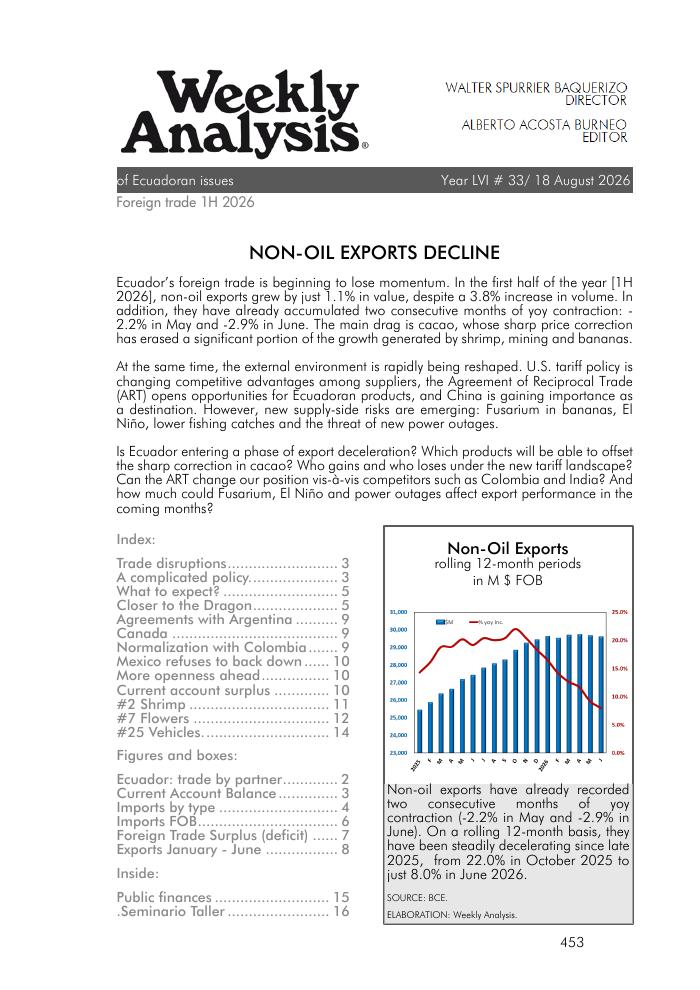
WA-2026-33: NON-OIL EXPORTS DECLINE
Ecuador’s foreign trade is beginning to lose momentum. In the first half of the year [1H 2026], non-oil exports grew by just 1.1% in value, despite a 3.8% increase in volume. In addition, they have already accumulated two consecutive months of yoy contraction: -2.2% in May and -2.9% in June. The main drag is cacao, whose sharp price correction has erased a significant portion of the growth generated by shrimp, mining and bananas. At the same time, the external environment is rapidly being reshaped. U.S. tariff policy is changing competitive advantages among suppliers, the Agreement of Reciprocal Trade (ART) opens opportunities for Ecuadoran products, and China is gaining importance as a destination. However, new supply-side risks are emerging: Fusarium in bananas, El Niño, lower fishing catches and the threat of new power outages. Is Ecuador entering a phase of export deceleration? Which products will be able to offset the sharp correction in cacao? Who gains and who loses under the new tariff landscape? Can the ART change our position vis-à-vis competitors such as Colombia and India? And how much could Fusarium, El Niño and power outages affect export performance in the coming months?
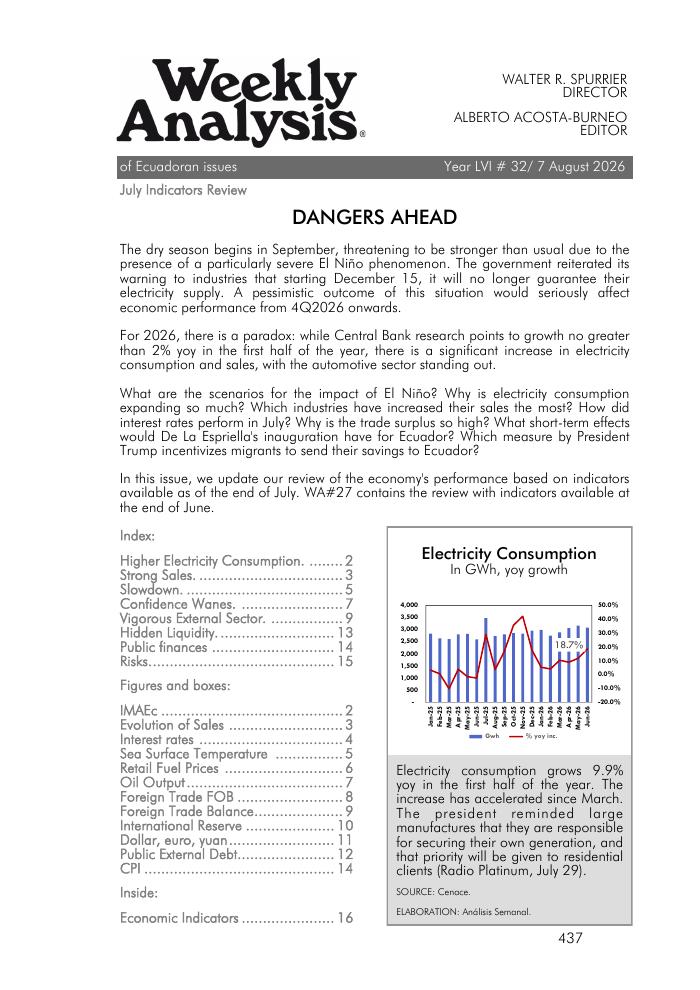
WA-2026-32: DANGERS AHEAD
The dry season begins in September, threatening to be stronger than usual due to the presence of a particularly severe El Niño phenomenon. The government reiterated its warning to industries that starting December 15, it will no longer guarantee their electricity supply. A pessimistic outcome of this situation would seriously affect economic performance from 4Q2026 onwards. For 2026, there is a paradox: while Central Bank research points to growth no greater than 2% yoy in the first half of the year, there is a significant increase in electricity consumption and sales, with the automotive sector standing out. What are the scenarios for the impact of El Niño? Why is electricity consumption expanding so much? Which industries have increased their sales the most? How did interest rates perform in July? Why is the trade surplus so high? What short-term effects would De La Espriella's inauguration have for Ecuador? Which measure by President Trump incentivizes migrants to send their savings to Ecuador? In this issue, we update our review of the economy's performance based on indicators available as of the end of July. WA#27 contains the review with indicators available at the end of June.
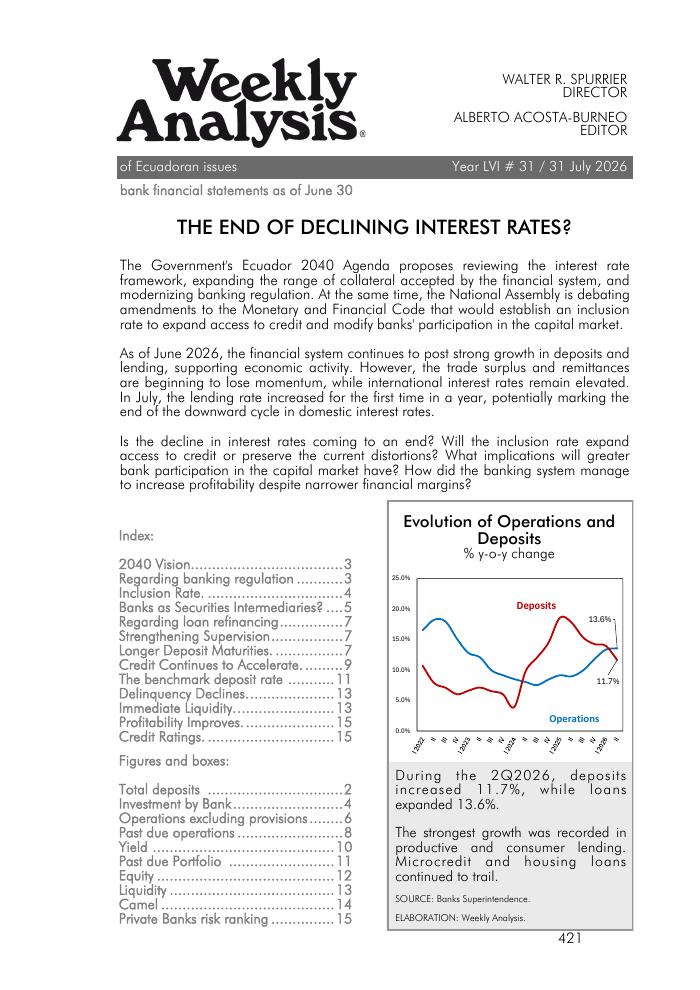
WA-2026-31: THE END OF DECLINING INTEREST RATES?
The Government's Ecuador 2040 Agenda proposes reviewing the interest rate framework, expanding the range of collateral accepted by the financial system, and modernizing banking regulation. At the same time, the National Assembly is debating amendments to the Monetary and Financial Code that would establish an inclusion rate to expand access to credit and modify banks' participation in the capital market. As of June 2026, the financial system continues to post strong growth in deposits and lending, supporting economic activity. However, the trade surplus and remittances are beginning to lose momentum, while international interest rates remain elevated. In July, the lending rate increased for the first time in a year, potentially marking the end of the downward cycle in domestic interest rates. Is the decline in interest rates coming to an end? Will the inclusion rate expand access to credit or preserve the current distortions? What implications will greater bank participation in the capital market have? How did the banking system manage to increase profitability despite narrower financial margins?